Guide to Foreign Tax Withholding on Dividends for U.S. Investors
Most countries keep part of the dividends their companies pay to U.S. investors. The standard rate runs from 0% in the U.K. to 35% in Switzerland, and tax treaties cut it to 15% for most developed markets.
In a taxable account, you can usually get that money back as a U.S. foreign tax credit. Retirement accounts are different. Most countries still withhold on dividends paid into an IRA or Roth IRA, with Canada as the main exception.
This matters for more investors than it might seem. Of the nearly 900 companies we rate with our Dividend Safety Scores, 72 pay dividends that we flag for foreign or Canadian withholding, including Enbridge, Nestlé, Roche and Royal Bank of Canada.
Below we cover what foreign withholding is, the rates by country, how treaties and the foreign tax credit work, what happens in retirement accounts, and how currency moves change your income.
What Is Foreign Dividend Withholding Tax?
U.S. companies generally do not withhold tax from dividends paid to U.S. residents. You receive the full payment and report it on your tax return.
Many foreign governments work differently. When a company based in their country pays a dividend to a shareholder who lives abroad, they take a cut before the money leaves. Your broker shows the dividend and the foreign tax withheld as separate lines, and both appear on your Form 1099-DIV.
That withholding reduces the cash you receive. How much it costs you in the end depends on the country, whether a tax treaty applies, and the kind of account you hold the stock in.
Dividend Withholding Tax Rates by Country
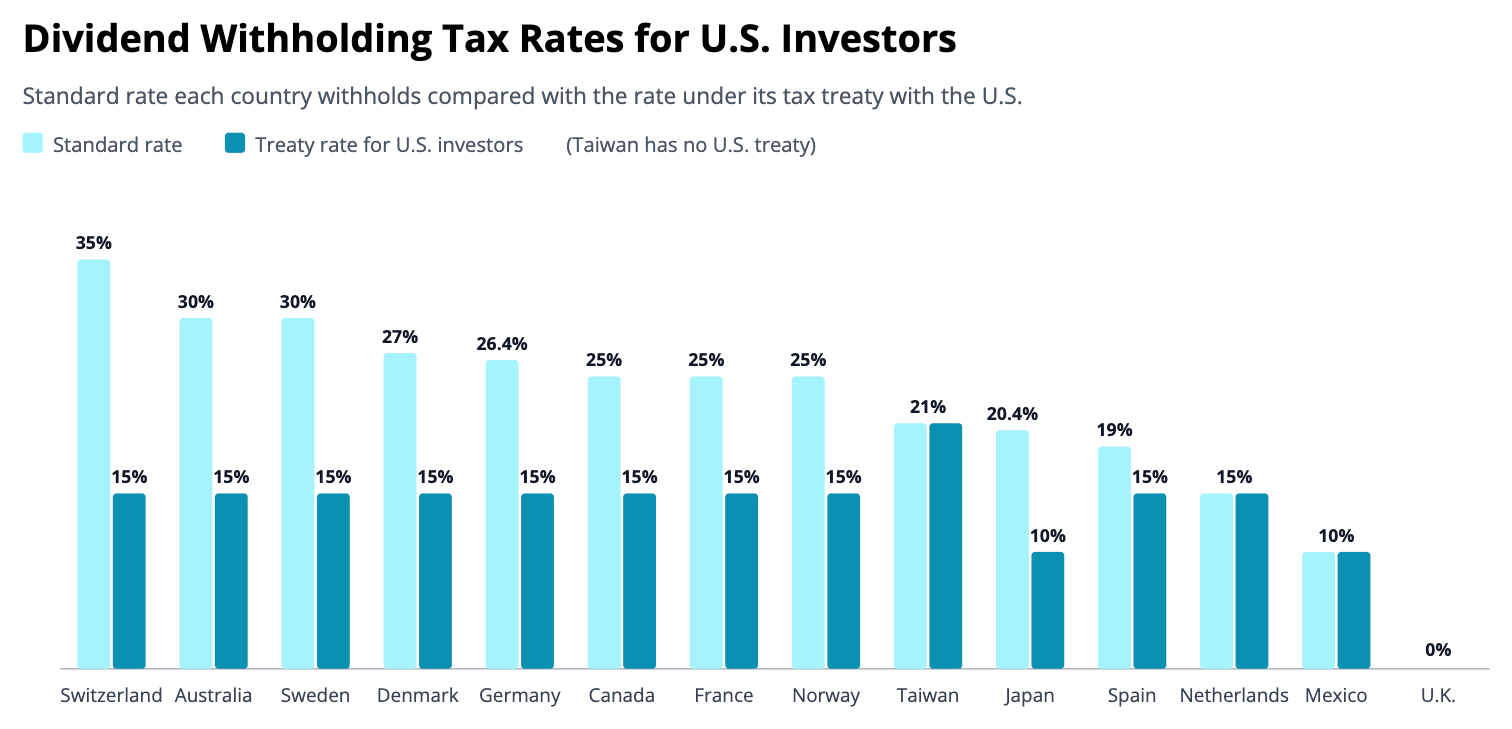
The standard rate varies widely. Switzerland withholds 35%, Australia and Sweden 30%, Germany about 26%, and Canada, France and Norway 25%, according to the withholding rates S&P Dow Jones Indices uses for its indexes as of April 2024. The U.K. withholds nothing.
Tax treaties bring most of those rates down. The U.S. has income tax treaties with dozens of countries, and most of them cap withholding on ordinary shareholders at 15%, according to the IRS tax treaty table. Japan's treaty rate is 10%. Taiwan has no U.S. treaty, so its 21% rate applies in full.
Australia has one wrinkle worth knowing. It does not withhold on the "franked" part of a dividend, the portion paid from profits that already bore Australian corporate tax, according to the Australian Taxation Office. Many large Australian companies pay fully franked dividends.
How Tax Treaties Lower the Rate, and When You Have to Reclaim It
A treaty rate is not always applied automatically. To get it at the source, your broker and the paying agent need to know you are a U.S. resident. Most large U.S. brokers handle this for countries such as Canada, but practices vary by country and by broker.
Some countries, Switzerland in particular, often withhold the full standard rate on U.S. holders, and the investor must file a reclaim with that country to recover the difference. Check your statements. If 35% came out of a Swiss dividend, you were charged 20 points more than the treaty rate.
That gap matters at tax time. The IRS lets you claim a credit only for the tax you legally owed under the treaty, not for extra tax that was withheld. In its own example, a country withholds 30% when the treaty rate is 15%, and only the 15% counts toward the credit, according to the IRS guidance on foreign taxes that qualify.
Ireland is another special case. Several large companies listed in the U.S. are based there, and Ireland's 25% dividend withholding tax does not apply to qualifying nonresidents who file the right declaration, according to Ireland's Revenue Commissioners. Revenue also describes a simplified process for U.S. residents who hold American Depositary Receipts.
How to Claim the Foreign Tax Credit on Dividends
Foreign tax withheld in a taxable account is not lost. The U.S. lets you subtract it from your own tax bill, either as a credit or as an itemized deduction. A credit is usually worth more because it reduces your tax dollar for dollar.
The simplest case covers most investors. If all your foreign income is passive income such as dividends, it is reported on a Form 1099-DIV or similar statement, and your creditable foreign taxes total $300 or less ($600 for joint filers), you can claim the credit directly on Form 1040 without filing Form 1116, according to the IRS instructions for Form 1116.
There is a trade-off. Under that simplified election, you cannot carry unused foreign taxes back or forward to other years.
Above those limits, you file Form 1116. The credit is then capped at your U.S. tax multiplied by your foreign-source taxable income divided by your total taxable income, according to the IRS explanation of how to figure the credit. Foreign tax you cannot use because of that cap may be carried back to the previous year and forward up to 10 years.
One more rule trips up short-term holders. Foreign tax on a dividend is not creditable unless you held the stock for at least 16 days during the 31-day period that begins 15 days before the ex-dividend date.
Foreign Dividends in IRAs and Roth IRAs
Holding foreign stocks in a retirement account usually does not avoid the withholding. Most countries still take their cut of dividends paid into an IRA or Roth IRA. If you hold foreign dividend stocks in a retirement account, ask a tax professional whether any of that withholding can be recovered.
Canada is the big exception. Under the U.S.-Canada treaty, dividends paid to U.S. IRAs, including Roth IRAs, can be exempt from Canadian withholding, according to the Depository Trust & Clearing Corporation's guide to Canadian tax relief. The U.K. withholds nothing to begin with.
That leads to a simple rule of thumb for many investors. Canadian, U.K. and U.S. dividend payers can generally go in either account type. Stocks from countries with high withholding, such as Switzerland, Germany and France, may fit better in taxable accounts, where the foreign tax credit can recover tax up to the treaty rate.
Currency Swings Also Change Your Foreign Dividend Income
Withholding is not the only thing that separates a foreign dividend from a U.S. one. Most foreign companies set their dividends in their home currency, so the dollars you receive rise and fall with exchange rates.
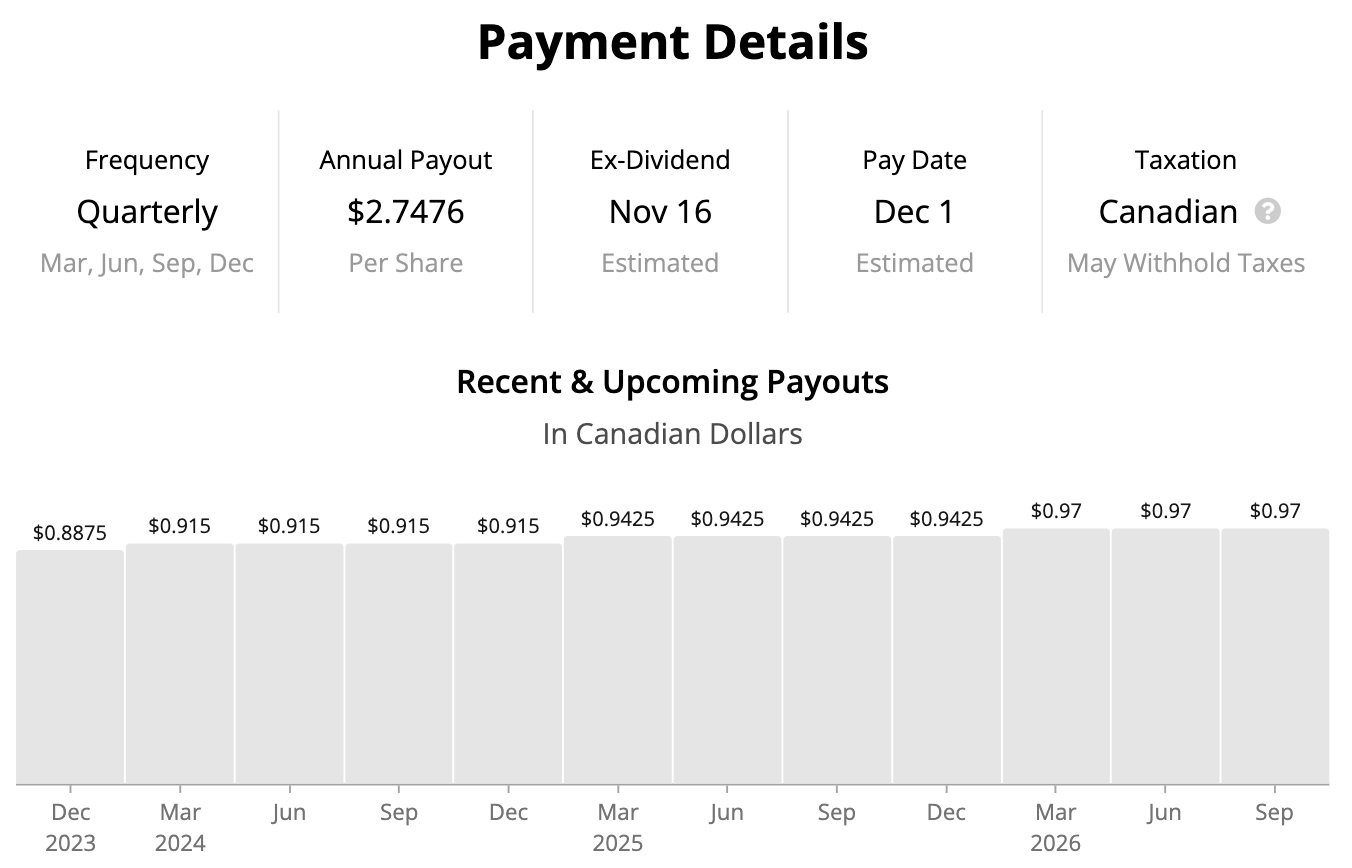
Our stock pages on Simply Safe Dividends flag this for every company we cover. Enbridge, the Canadian pipeline operator, has raised its quarterly dividend each year in Canadian dollars, from C$0.8875 in late 2023 to C$0.97 in 2026. What U.S. holders receive in dollars depends on the exchange rate on each payment date.
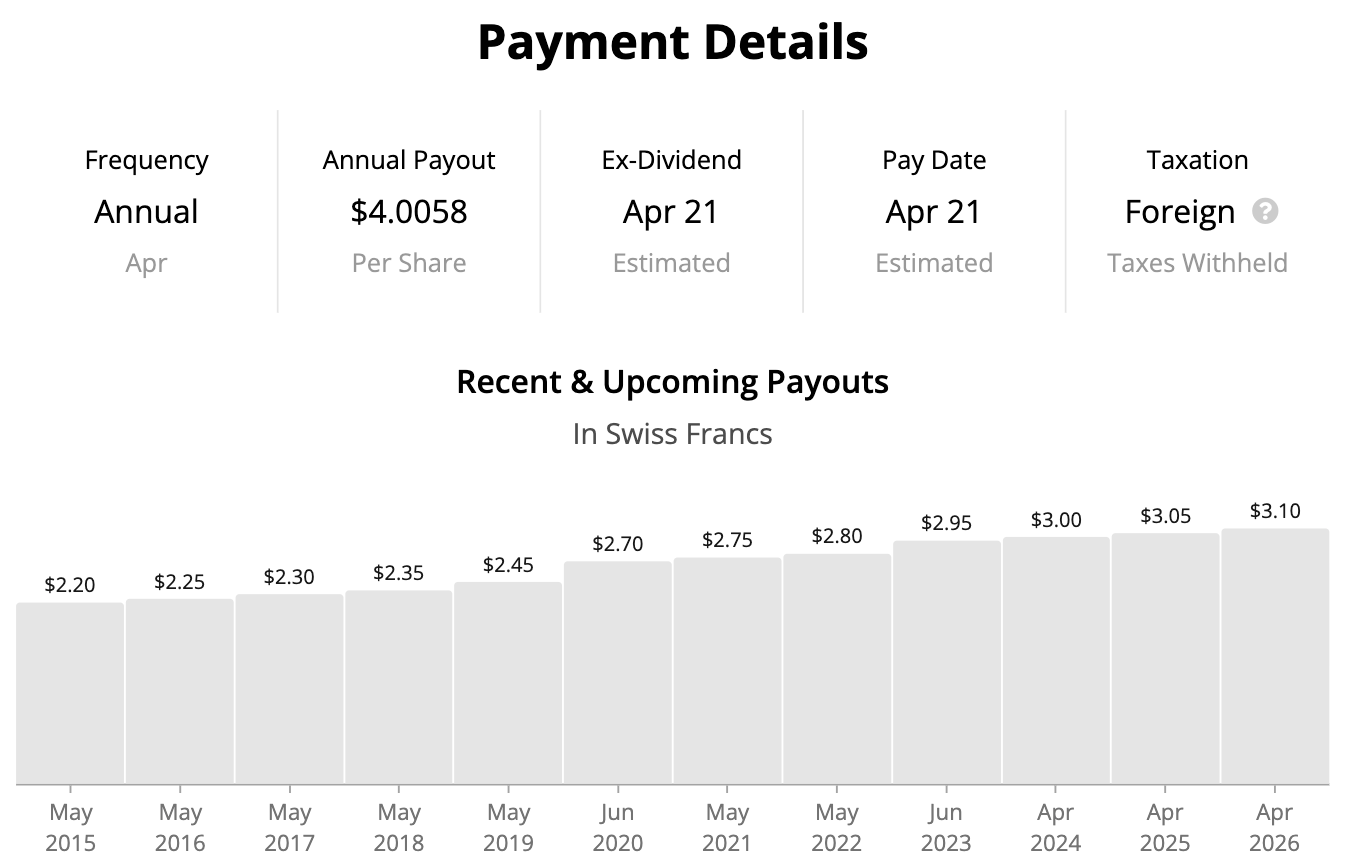
Nestlé tells a similar story in Swiss francs. It has raised its annual dividend every year since at least 2015, from CHF 2.20 to CHF 3.10 per share in 2026. Its dividend comes with Swiss withholding and pays once a year, which makes income planning harder than with a U.S. company that pays quarterly.
Foreign Dividend Stocks We Rate
Of the 72 companies we flag for foreign withholding, 47 are Canadian. Switzerland is next with six, followed by Germany with four.
Their dividend safety looks much like the rest of our universe. Thirty-five of the 72, or 49%, earn a Safe or Very Safe Dividend Safety Score. Across all the stocks we rate, the share is 48%.
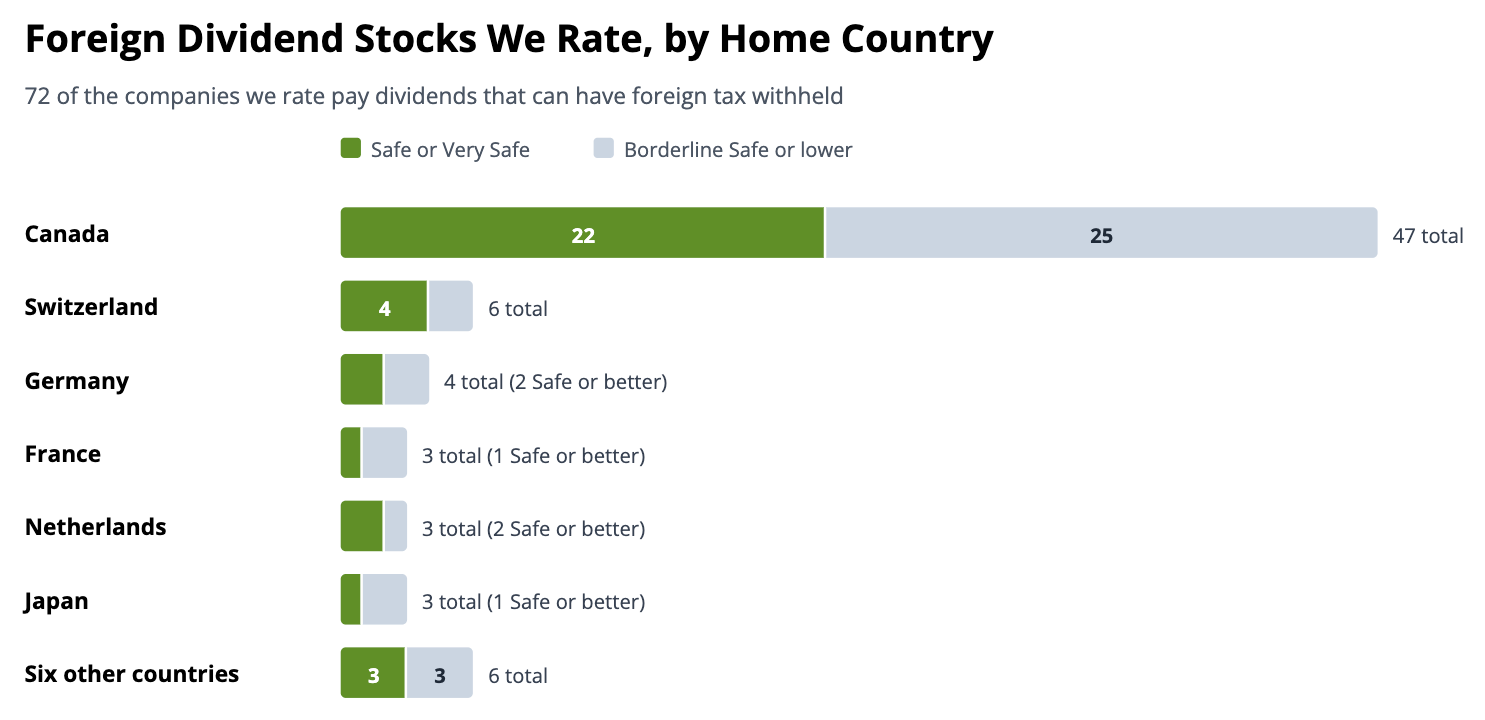
The highest-rated names include Roche, SAP and Sony, which earn Very Safe Dividend Safety Scores, along with Canadian National Railway. Canada's big banks, such as Royal Bank of Canada and Toronto-Dominion Bank, earn Safe Dividend Safety Scores, as does Enbridge. Many others land in Borderline Safe territory, including TotalEnergies and Toyota.
For investors who would rather skip the paperwork, U.S. multinationals offer another route abroad. Many of the S&P 500 Dividend Aristocrats earn a large share of their sales overseas while paying dividends with no foreign withholding at all.
U.S. Withholding Tax on Dividends for Foreign Investors
The rules run the other way too. The U.S. withholds 30% of dividends paid to nonresidents unless a treaty lowers it, and most treaties cut it to 15% for ordinary shareholders, according to the IRS tax treaty table.
To claim the treaty rate, a foreign individual gives their broker IRS Form W-8BEN, which certifies their country of residence. Without it, the full 30% generally applies.
Frequently Asked Questions
What is foreign tax withholding on dividends?
It is tax a foreign country takes from dividends its companies pay to investors who live elsewhere. Standard rates range from 0% in the U.K. to 35% in Switzerland, and U.S. tax treaties cut them to 15% for most developed countries.
It is tax a foreign country takes from dividends its companies pay to investors who live elsewhere. Standard rates range from 0% in the U.K. to 35% in Switzerland, and U.S. tax treaties cut them to 15% for most developed countries.
What is the dividend withholding tax rate by country?
Common standard rates include 35% in Switzerland, 30% in Australia and Sweden, about 26% in Germany, 25% in Canada and France, about 20% in Japan, 15% in the Netherlands and 0% in the U.K. Under U.S. tax treaties, most of these fall to 15% for U.S. investors, and Japan's falls to 10%.
Common standard rates include 35% in Switzerland, 30% in Australia and Sweden, about 26% in Germany, 25% in Canada and France, about 20% in Japan, 15% in the Netherlands and 0% in the U.K. Under U.S. tax treaties, most of these fall to 15% for U.S. investors, and Japan's falls to 10%.
Can I get foreign tax withheld on dividends back?
Usually, in a taxable account. You can claim a U.S. foreign tax credit for tax up to the treaty rate. If you have $300 or less in creditable foreign taxes ($600 for joint filers), you can claim it on Form 1040 without Form 1116.
Usually, in a taxable account. You can claim a U.S. foreign tax credit for tax up to the treaty rate. If you have $300 or less in creditable foreign taxes ($600 for joint filers), you can claim it on Form 1040 without Form 1116.
Do I pay foreign withholding tax in an IRA?
Usually yes. Most countries withhold on dividends paid into IRAs and Roth IRAs. Canada is the main exception, since U.S. IRAs and Roth IRAs can be exempt from Canadian withholding. The U.K. does not withhold on dividends at all.
Usually yes. Most countries withhold on dividends paid into IRAs and Roth IRAs. Canada is the main exception, since U.S. IRAs and Roth IRAs can be exempt from Canadian withholding. The U.K. does not withhold on dividends at all.
How are Canadian dividends taxed for U.S. investors?
Canada withholds 25% by default and 15% under the U.S. treaty in a taxable account, which you can usually recover as a foreign tax credit. In an IRA or Roth IRA, Canadian dividends can be exempt from withholding.
Canada withholds 25% by default and 15% under the U.S. treaty in a taxable account, which you can usually recover as a foreign tax credit. In an IRA or Roth IRA, Canadian dividends can be exempt from withholding.
What is the U.S. withholding tax on dividends for foreign investors?
The U.S. withholds 30% by default. Most tax treaties lower it to 15% for individual investors who give their broker IRS Form W-8BEN.
The U.S. withholds 30% by default. Most tax treaties lower it to 15% for individual investors who give their broker IRS Form W-8BEN.
How many foreign dividend stocks does Simply Safe Dividends rate?
We rate 72 companies whose dividends can have foreign tax withheld, 47 of them Canadian. Thirty-five earn a Safe or Very Safe Dividend Safety Score.
We rate 72 companies whose dividends can have foreign tax withheld, 47 of them Canadian. Thirty-five earn a Safe or Very Safe Dividend Safety Score.
Closing Thoughts on Dividend Withholding Tax
Foreign withholding sounds worse than it usually is. In a taxable account, treaties and the foreign tax credit recover most or all of it, especially for investors under the $300 or $600 limit.
The trickier cases are retirement accounts, where most countries still withhold, countries that over-withhold and require a reclaim, and currency swings. Knowing which of your holdings are affected is the first step. Our guide to taxes on dividends covers how U.S. dividends themselves are taxed.
Our online tools flag every foreign-taxed holding in your portfolio, show the Dividend Safety Score of each one, and track how much income each position produces. You can see how it works here. Thanks for reading!