Altria (MO) Dividend: Is It Safe?
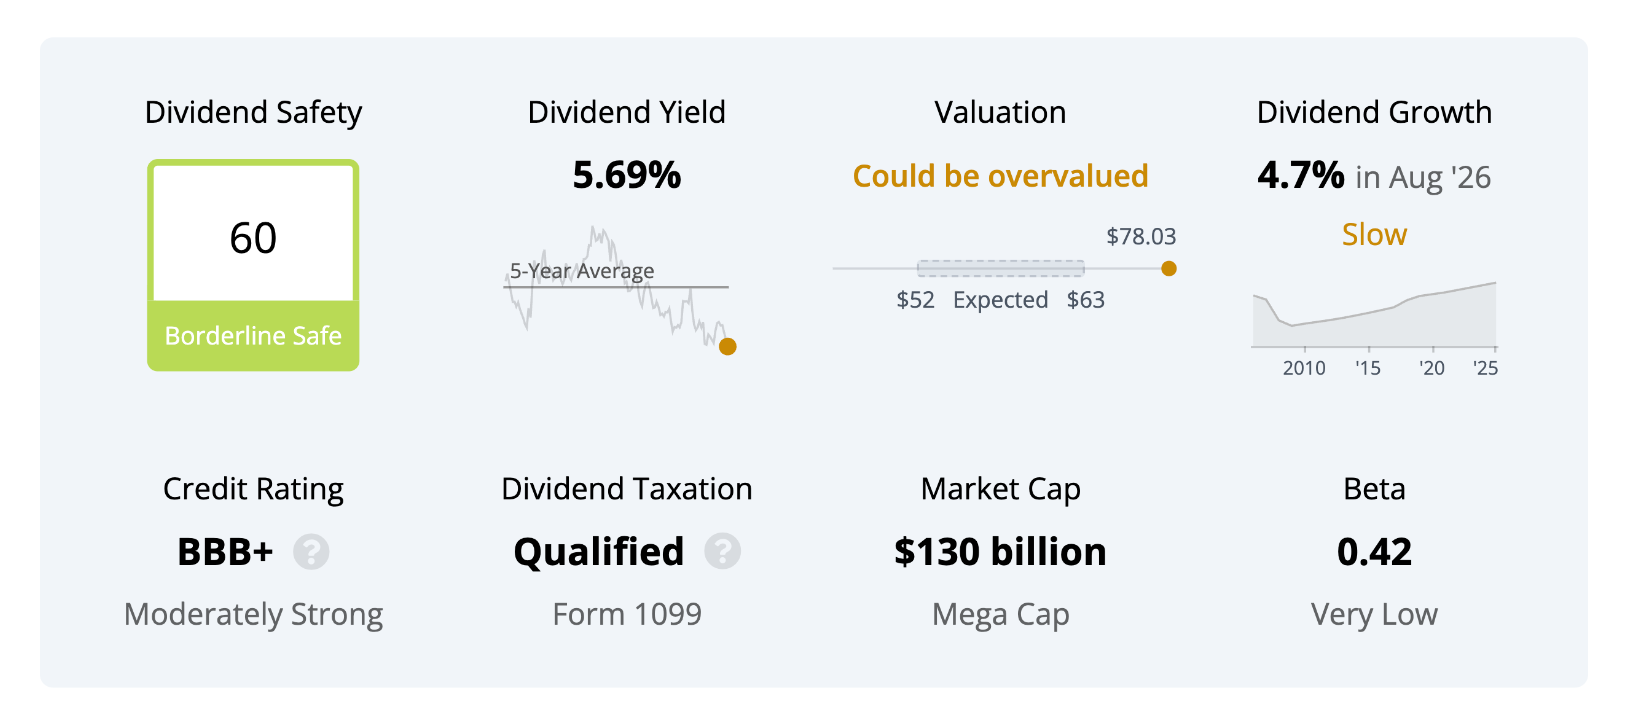
Altria's dividend looks secure for at least the next several years. We rate it Borderline Safe, meaning moderate risk of a cut over a full economic cycle, because the business that pays it, U.S. cigarettes, is slowly shrinking.
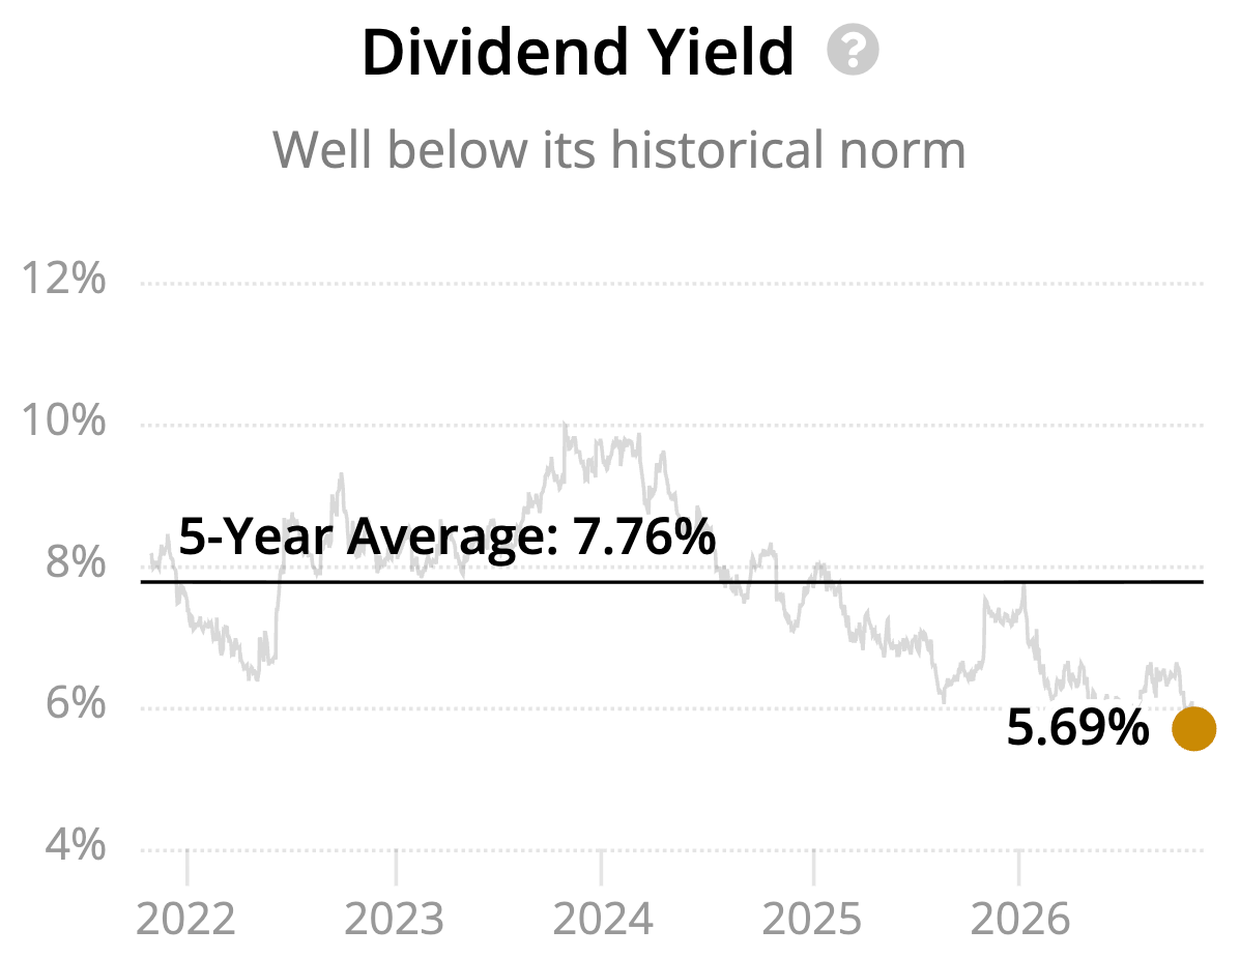
The near-term numbers are solid. Altria yields 5.7%, paying $4.44 per share a year in quarterly installments. It pays out about 75% of its adjusted earnings, carries little debt, and raised its dividend for the 61st time in 57 years in August 2026.
The risk is further out. It depends on how long Marlboro's price increases can outrun falling cigarette volumes, and whether Altria ever builds a smoke-free business big enough to replace them.
Here is Altria's dividend profile on our site as of the October 30, 2026 close.
Why We Rate Altria's Dividend Borderline Safe
Altria earns nearly all of its money selling Marlboro cigarettes in the U.S., along with smaller brands like Copenhagen chewing tobacco and Black & Mild cigars.
For decades it has raised prices faster than volumes fall, which nicotine's addictiveness makes possible, and returned most of the cash to shareholders.
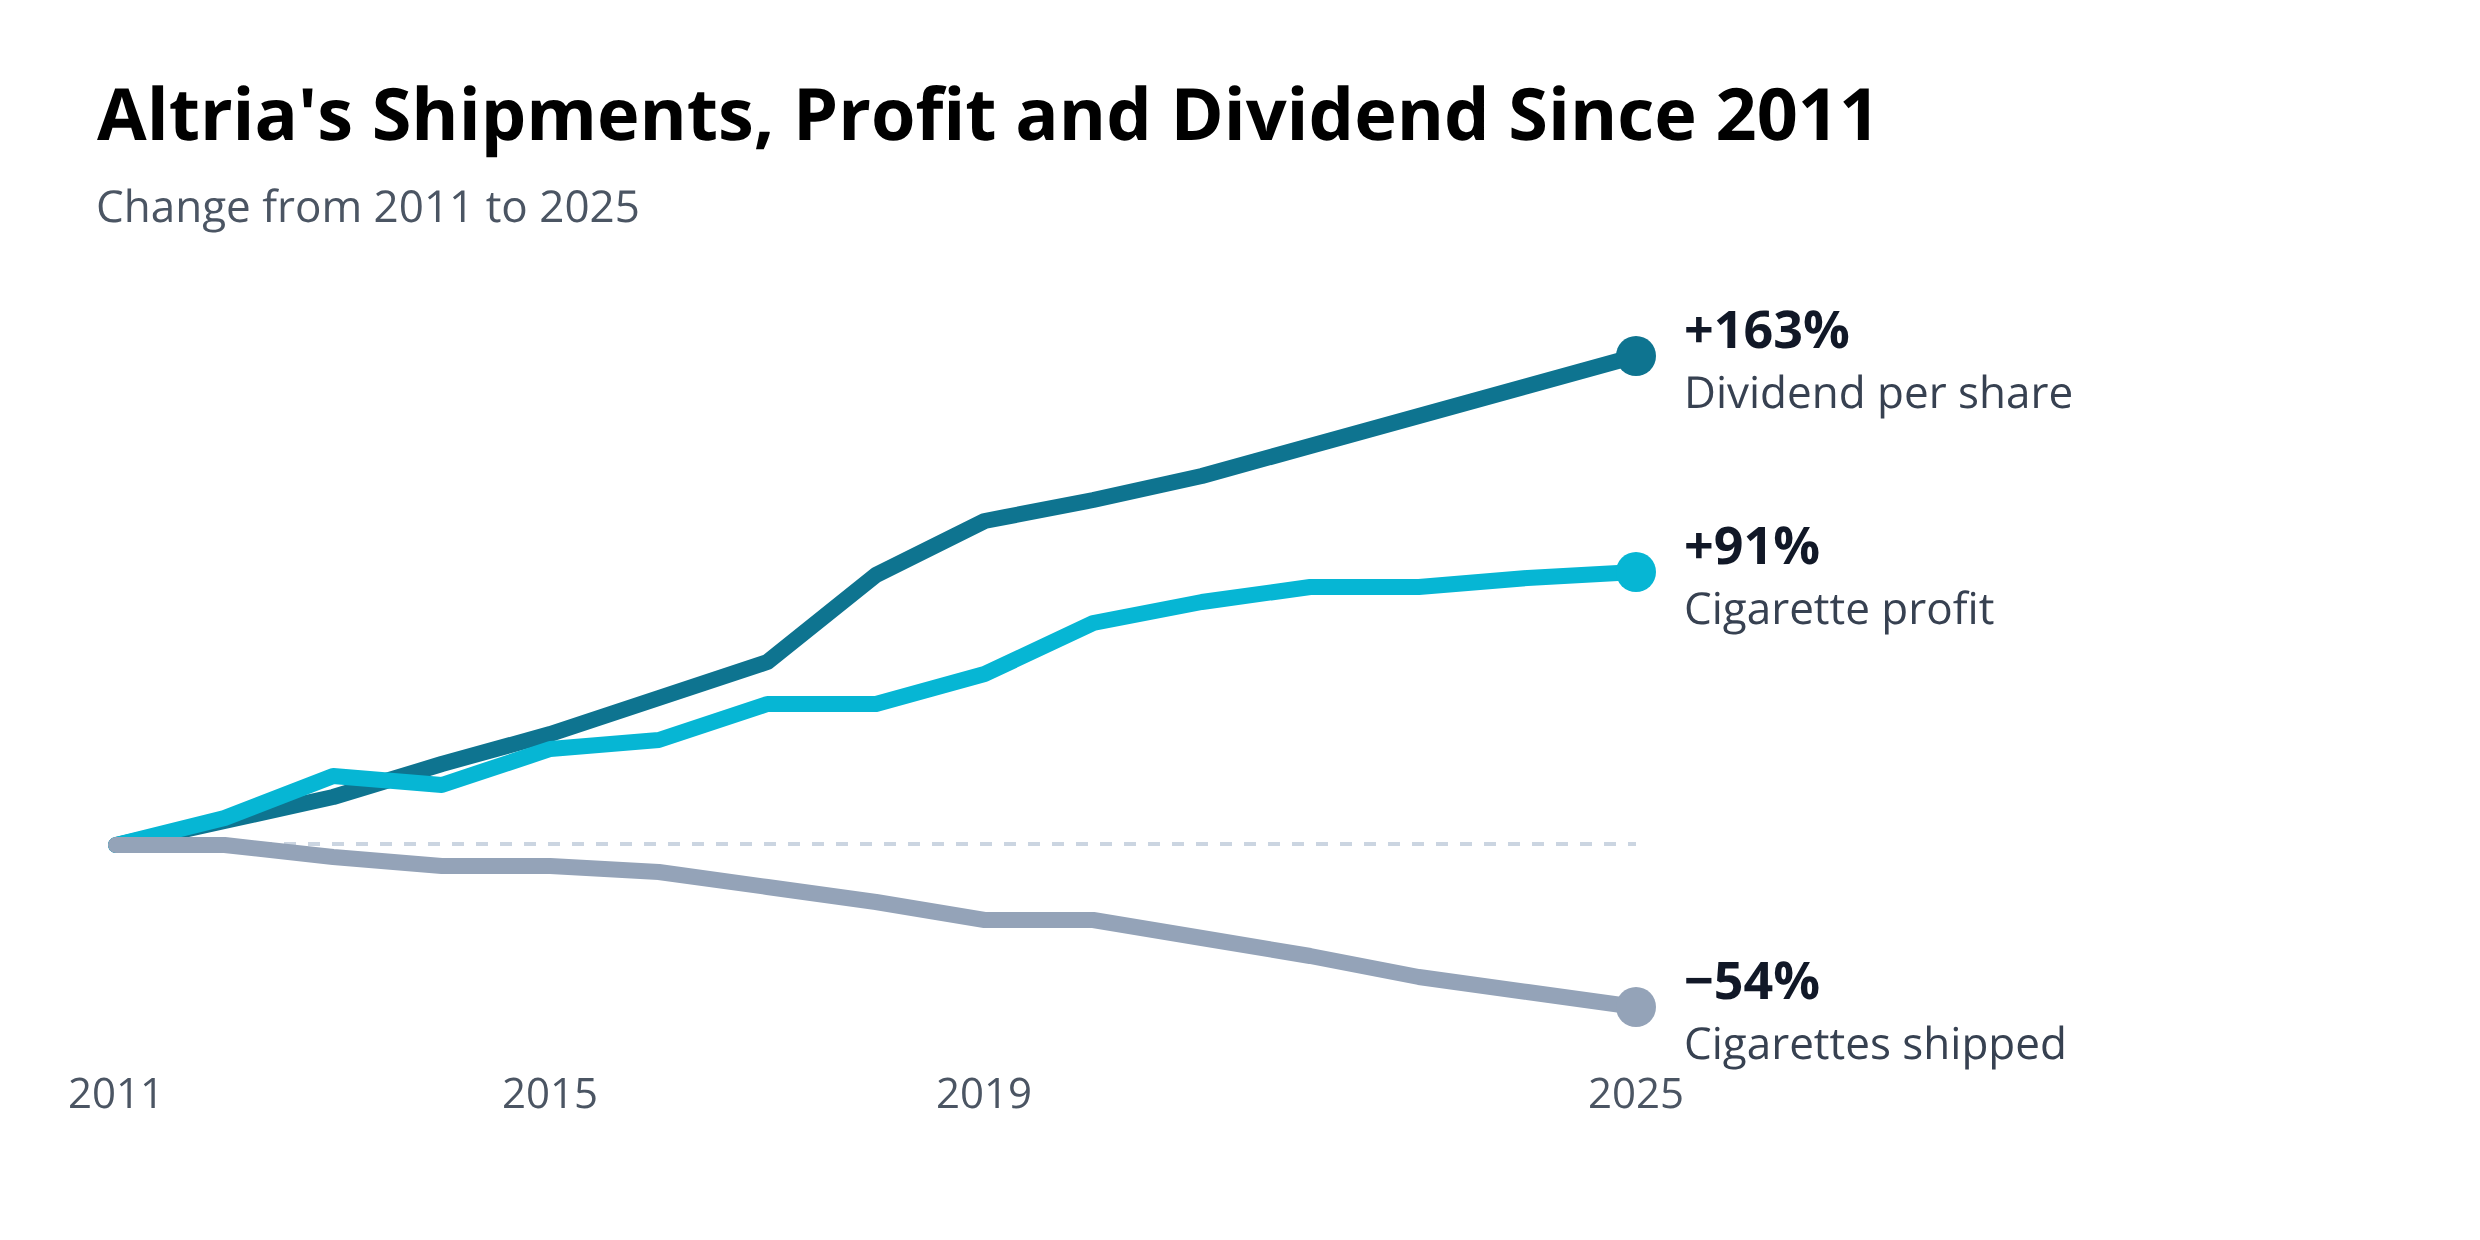
That approach has worked well. From 2011 through 2025, Altria's U.S. cigarette shipments fell 54%, from 135 billion to 62 billion. Yet the profit of its cigarette business rose 91% over the same years, and its dividend per share grew 163%.
Put simply, Altria now takes in about two and a half times as much money per cigarette as it did in 2011, after excise taxes.
Steady price increases did most of the work, lifting the cigarette business's adjusted operating margin from 40% to 63%.
Lower settlement costs helped, too. The payments Altria owes states under the 1998 tobacco settlement are tied to how many cigarettes it ships, so that cost shrinks as volumes fall.
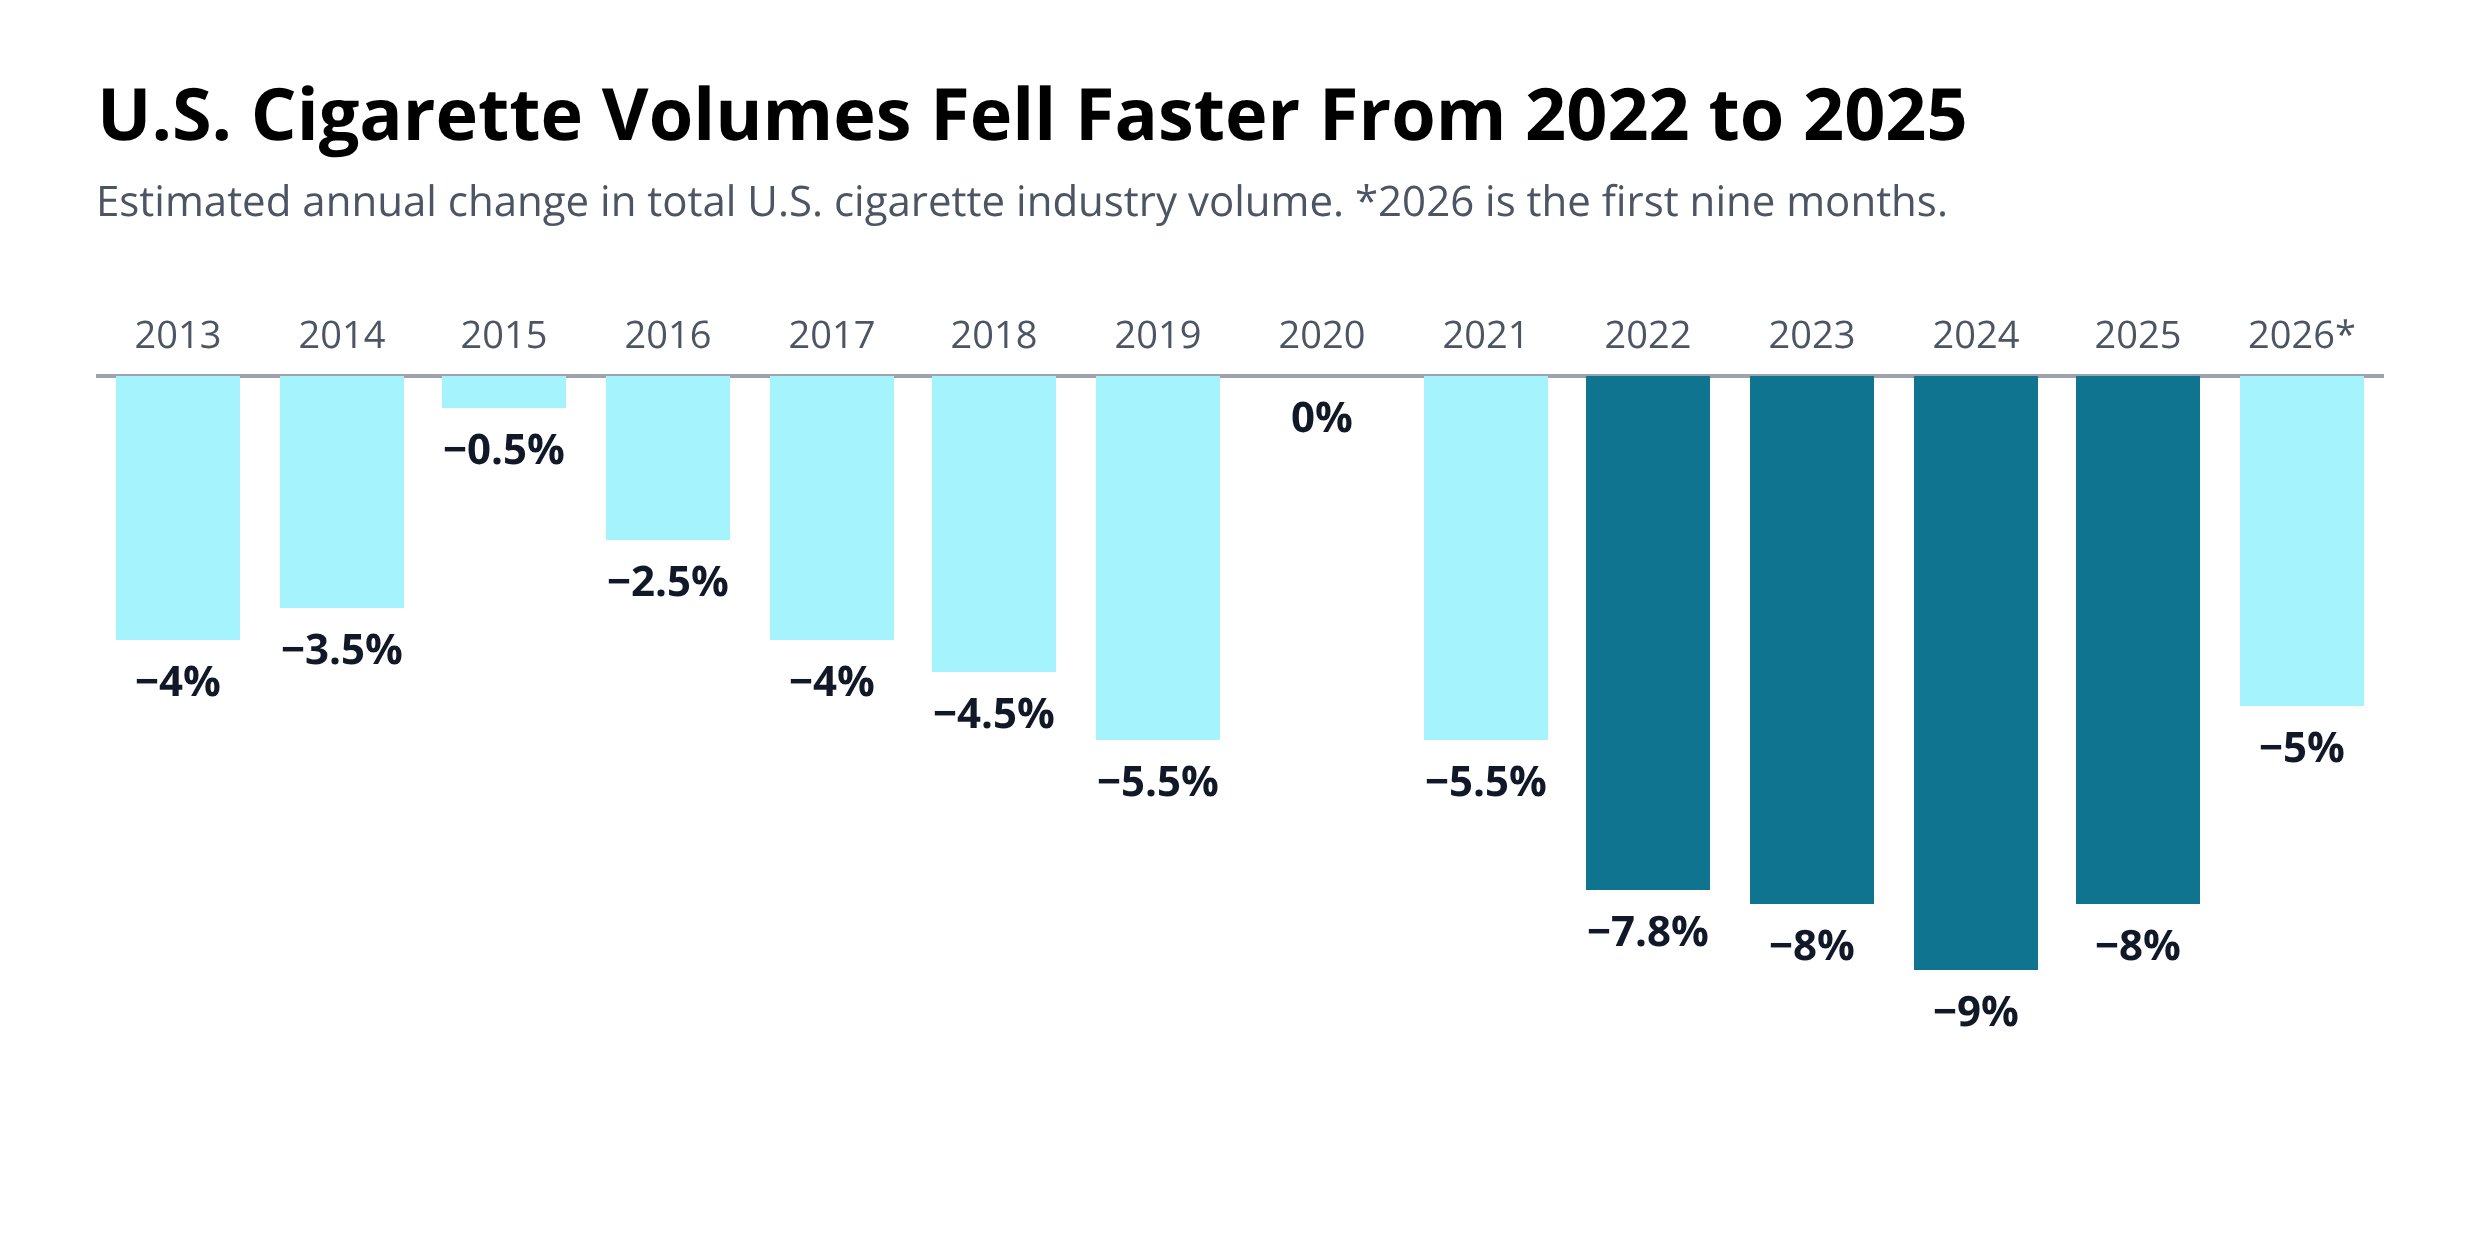
However, from 2022 through 2025 that dynamic came under strain. Industry cigarette volumes, which had typically fallen 3% to 5% a year, began dropping 8% to 9% a year as cheap illegal vapes flooded the market.
At the same time, the FDA had proposed banning menthol cigarettes, which make up roughly a third of U.S. cigarette sales, and capping nicotine at levels too low to sustain addiction. By early 2024 the stock traded at just 8 times earnings.
All three threats have since faded. The FDA withdrew the menthol ban in January 2025, the nicotine cap was shelved, and a federal crackdown on illegal vapes has slowed the decline in cigarette volumes back toward its old pace. Altria estimates industry cigarette volumes fell about 5% in the first nine months of 2026, back in line with the pre-2022 trend.
Most of that improvement came from Washington, not from Altria's own business. The stock has nearly doubled since early 2024, but little of that gain reflects anything Altria did.
That improvement is why we raised Altria's Dividend Safety Score to the top of our Borderline Safe range in July 2026. It reflects more confidence that the dividend is secure for the next several years, not a more optimistic view of Altria's long-term growth.
Altria's Payout Ratio
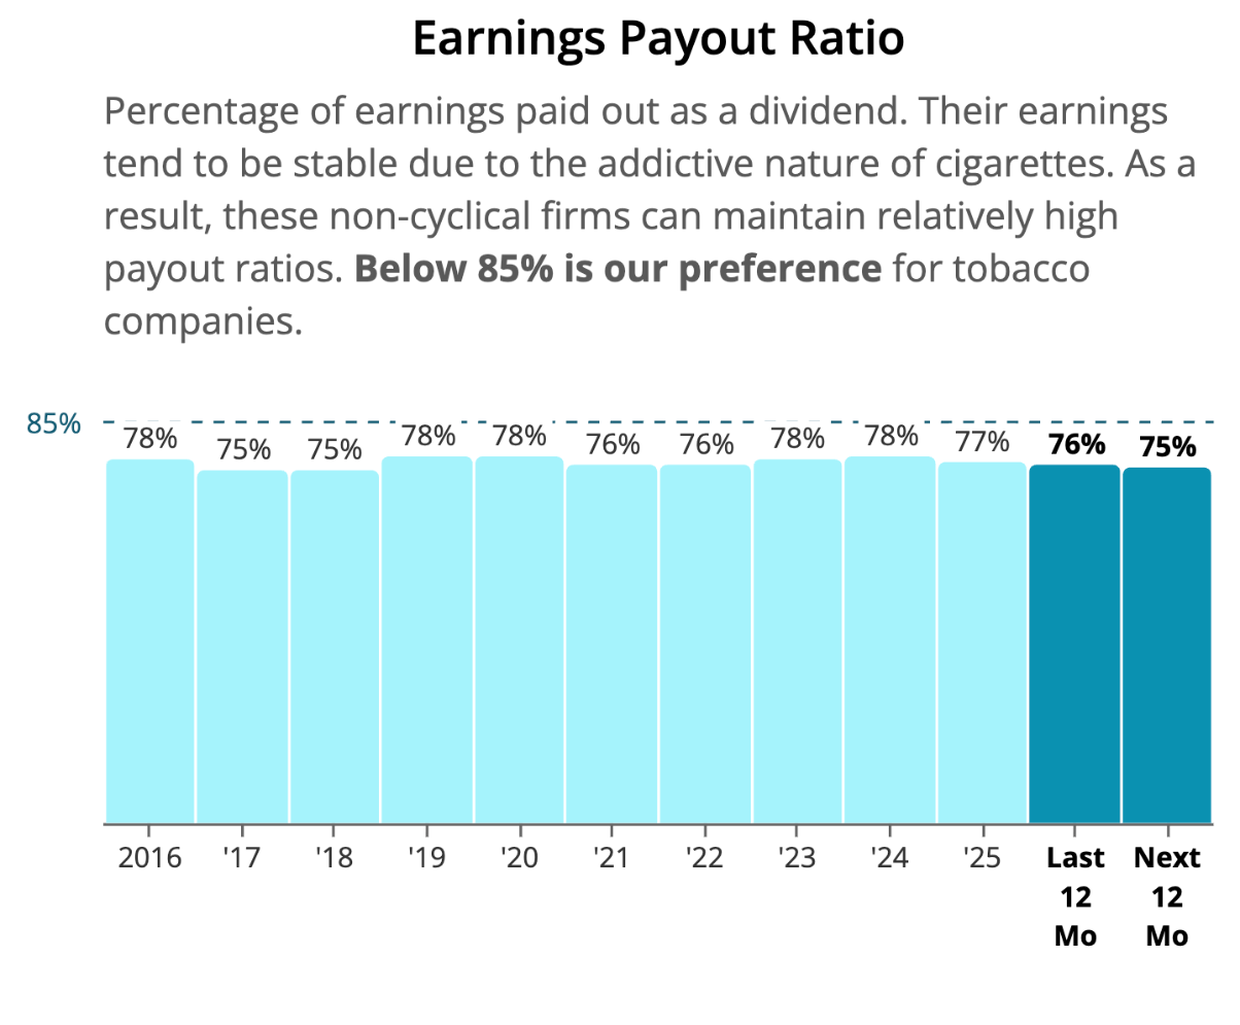
Altria has paid out a steady 75% to 78% of its adjusted earnings as dividends for the past decade, and we expect about 75% over the next 12 months. That is high for most companies but normal for a tobacco business with very stable earnings and little need to reinvest.
The company targets mid-single-digit annual dividend growth through 2028, roughly in line with its earnings growth. Altria raised its 2026 adjusted earnings guidance when it reported third-quarter results on October 29, representing a 4.5% to 6% increase over 2025.
Altria's Debt Profile
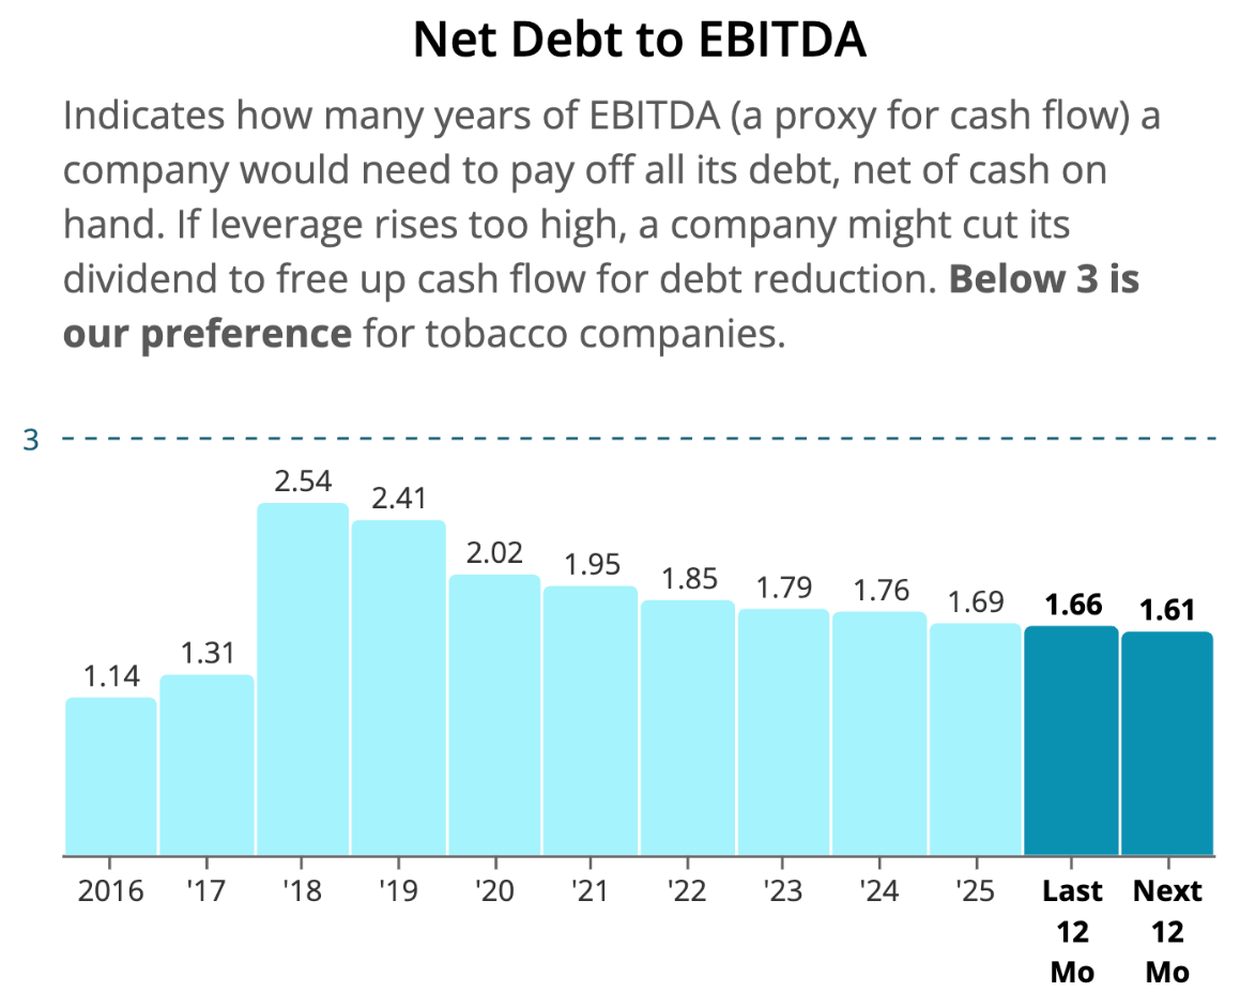
Altria's balance sheet is a strength, though it still reflects the Juul deal. Altria borrowed to fund that $12.8 billion investment in 2018, and its net debt roughly doubled to about $24 billion.
It has since worked that down to about $21 billion, or about 1.6 times EBITDA, which is low for a business this predictable. Altria also holds a BBB+ credit rating.
That gives Altria room to keep paying and raising its dividend through a bad year without straining its finances.
Altria's Dividend History
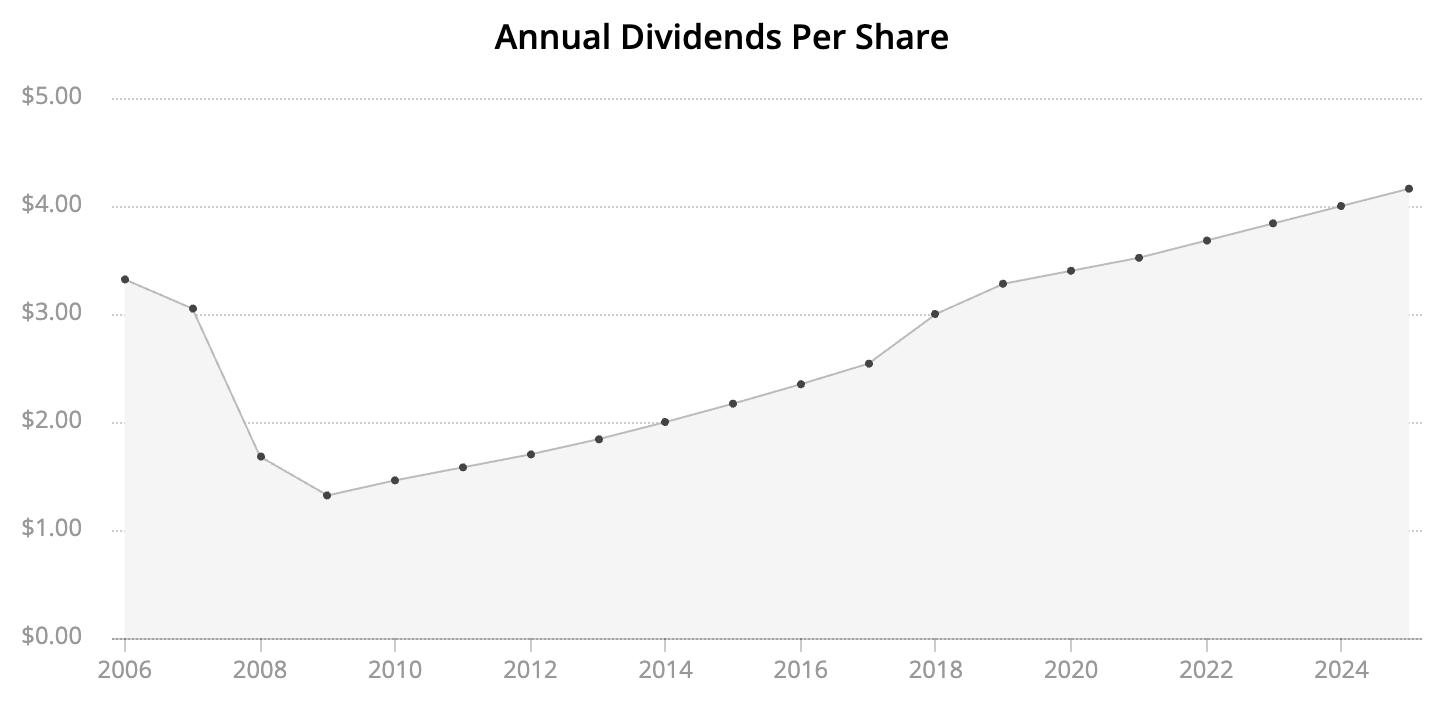
Altria has raised its dividend 61 times in the past 57 years. The drop on the chart in 2008 is not a cut. That year Altria spun off Philip Morris International, and shareholders received PMI shares whose dividends more than made up the difference, so we treat Altria's dividend record as unbroken.
Since 2009 the payout has risen every year, though growth has slowed to about 4% a year over the past five years. Altria's latest raise, in August 2026, was 4.7%.
Few companies hand back as much of their cash. From 2011 through 2025, Altria generated $99.6 billion of cash from operations and returned 99% of it to shareholders: $79.0 billion in dividends and $19.9 billion in buybacks, which shrank its share count by 18%.
What Could Threaten Altria's Dividend
Nothing points to a cut in the next few years. The bigger question is what Altria looks like in 10 or 20 years.
Smokers have more ways to quit. The FDA has authorized flavored e-cigarettes for adults, allowed Philip Morris International to say its Zyn nicotine pouches are less harmful than smoking, and cleared its IQOS heated tobacco device. These legal alternatives, backed by big marketing budgets, seem likely to keep pulling smokers away from cigarettes.
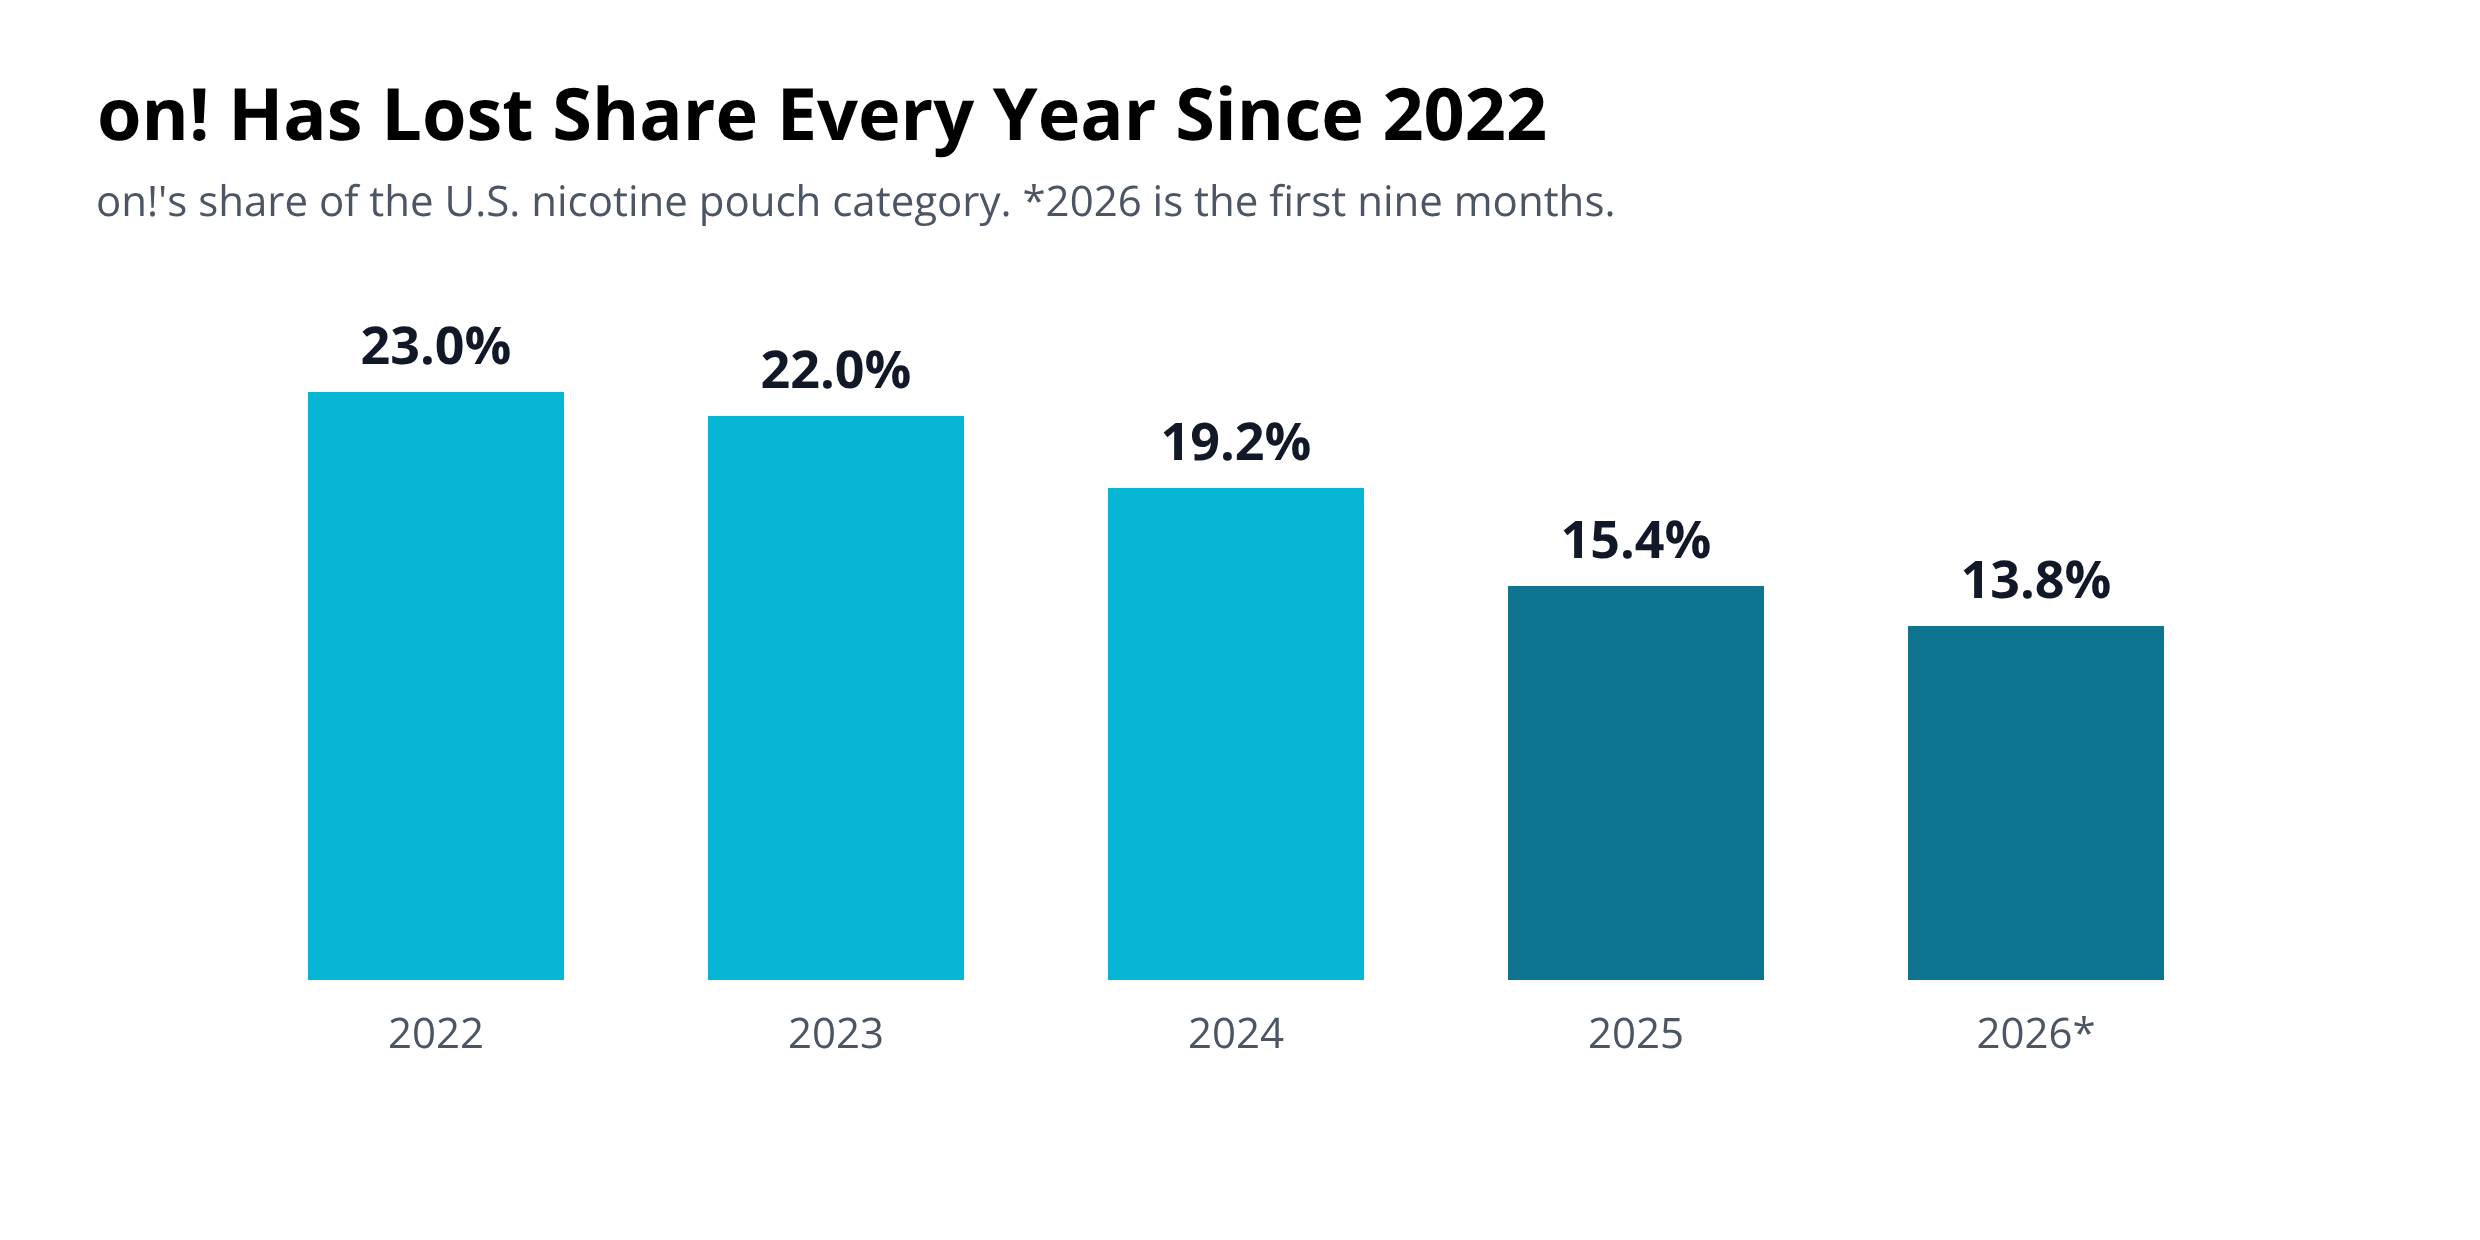
Altria largely doesn't own what smokers are switching to. Its on! nicotine pouch, bought in 2019, has steadily lost ground to Philip Morris International's Zyn, falling from 23% of the pouch category in 2022 to 13.8% in the first nine months of 2026.
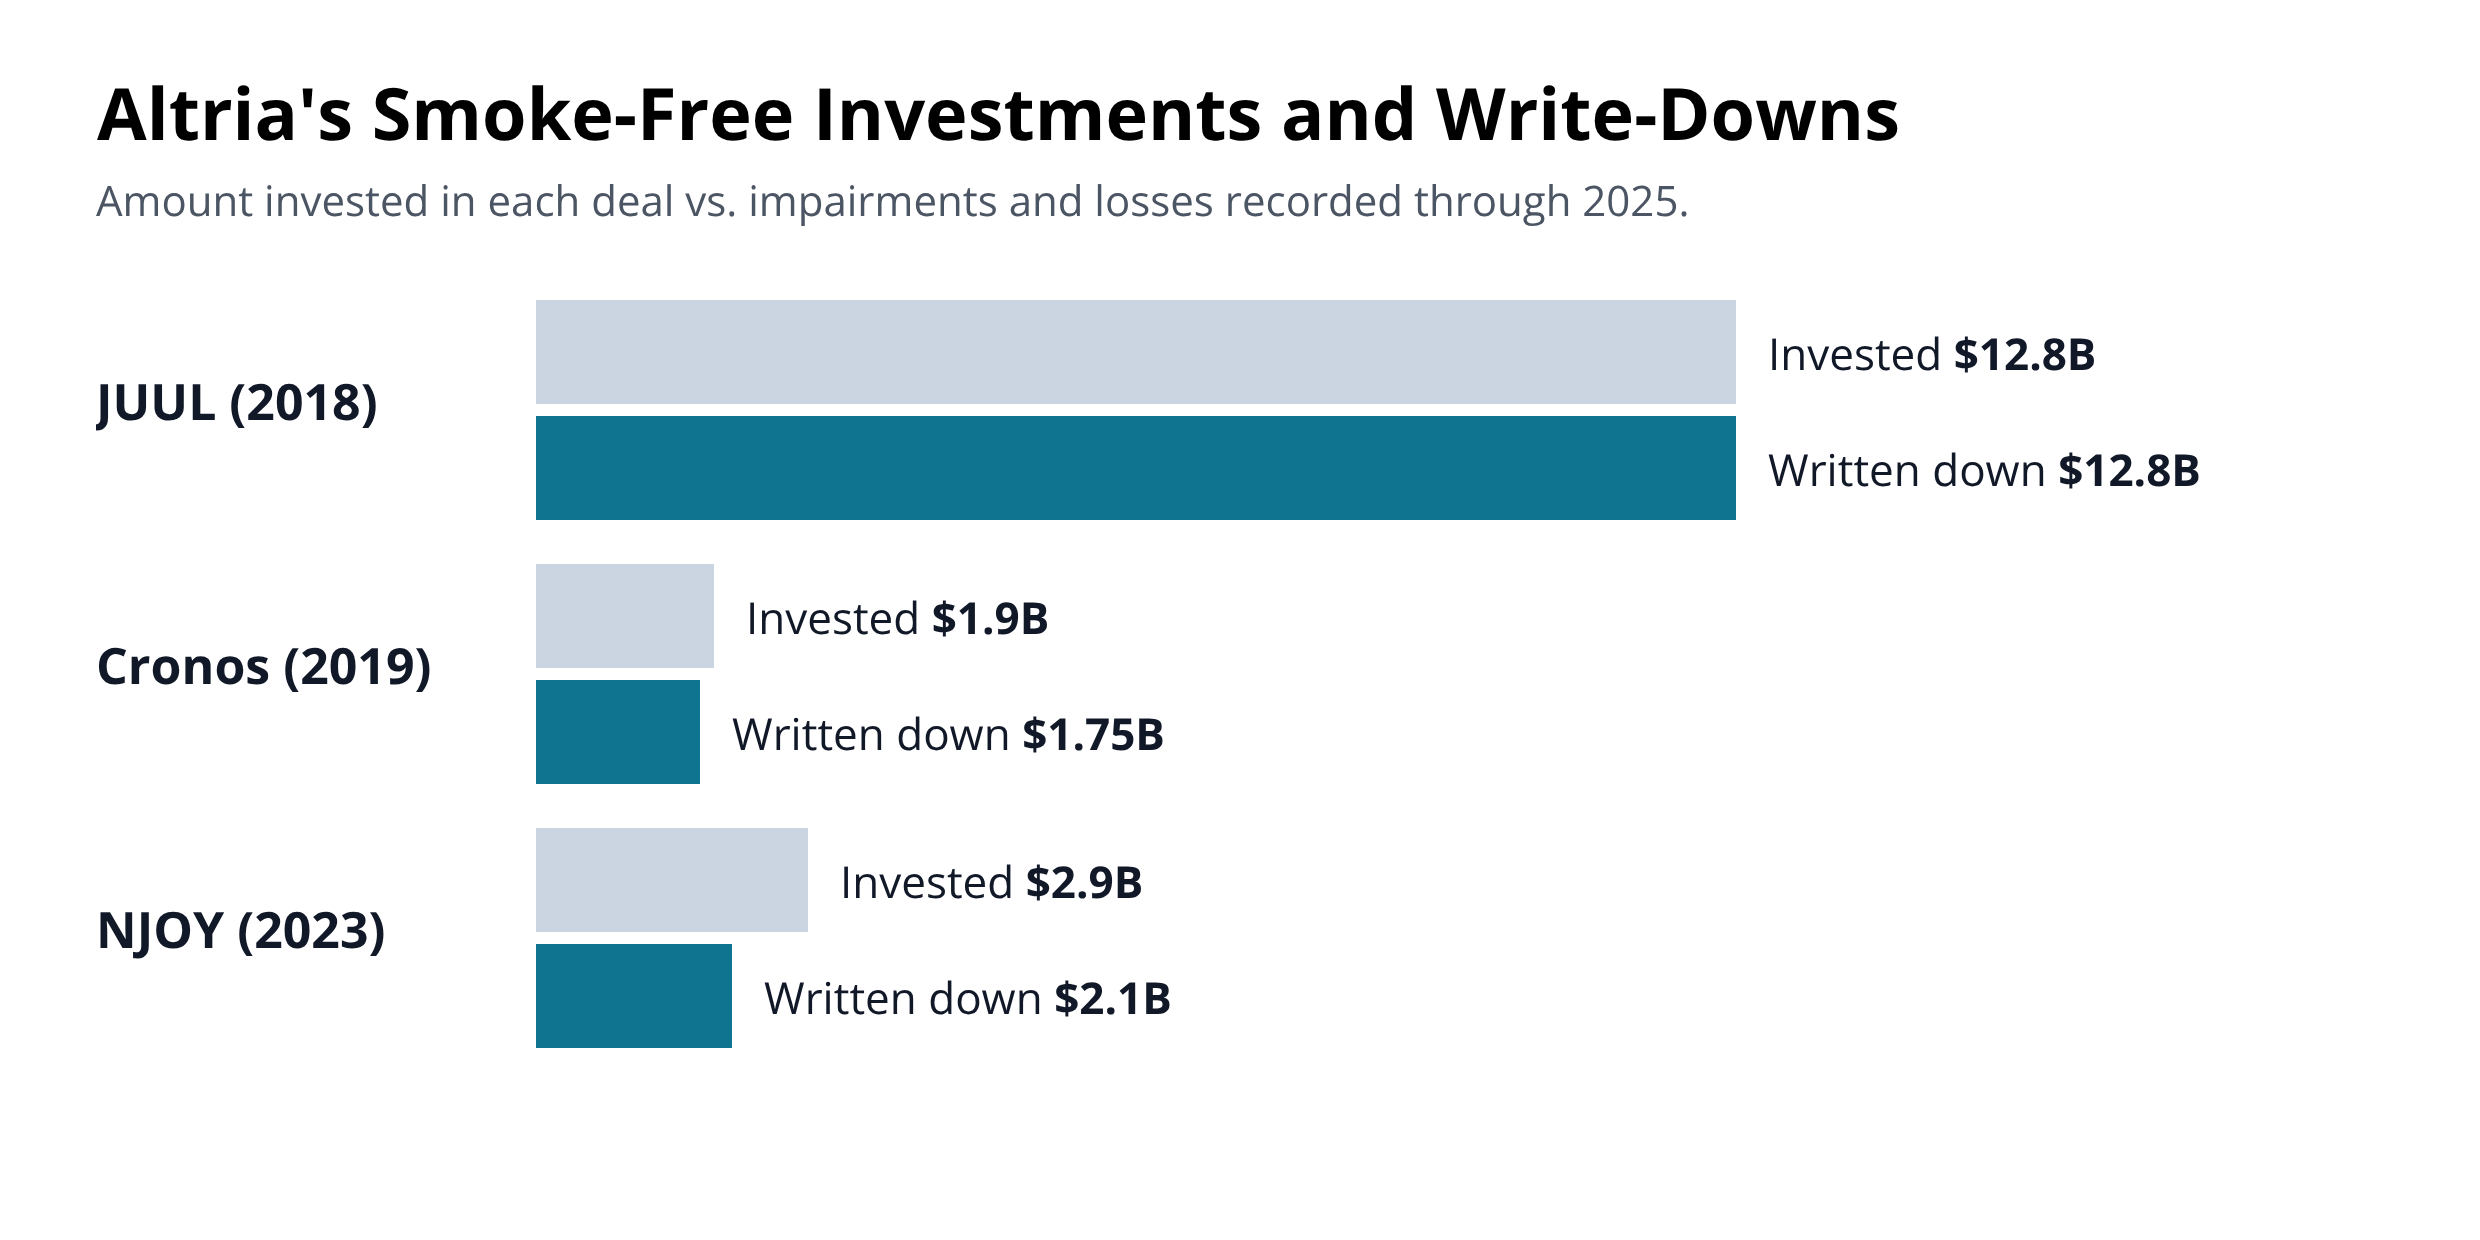
Meanwhile, its NJOY e-cigarettes were pulled from shelves after a patent loss to Juul and are not expected back in 2026. Altria paid about $2.9 billion for NJOY in 2023 and wrote off $2.1 billion of it in 2025.
That followed the $12.8 billion Juul investment, which was written off entirely, and a $1.9 billion stake in cannabis company Cronos that has lost most of its value.
In all, about $17.6 billion went into these three investments, and most of it has been written off. Altria no longer stands behind its goal of doubling smoke-free revenue by 2028.
Management points out that total U.S. nicotine use across cigarettes, pouches and vapes grew about 2.5% last year, and that Altria holds the largest share of that combined market. But most of Altria's share comes from shrinking cigarette sales, while the growing categories belong mostly to competitors.
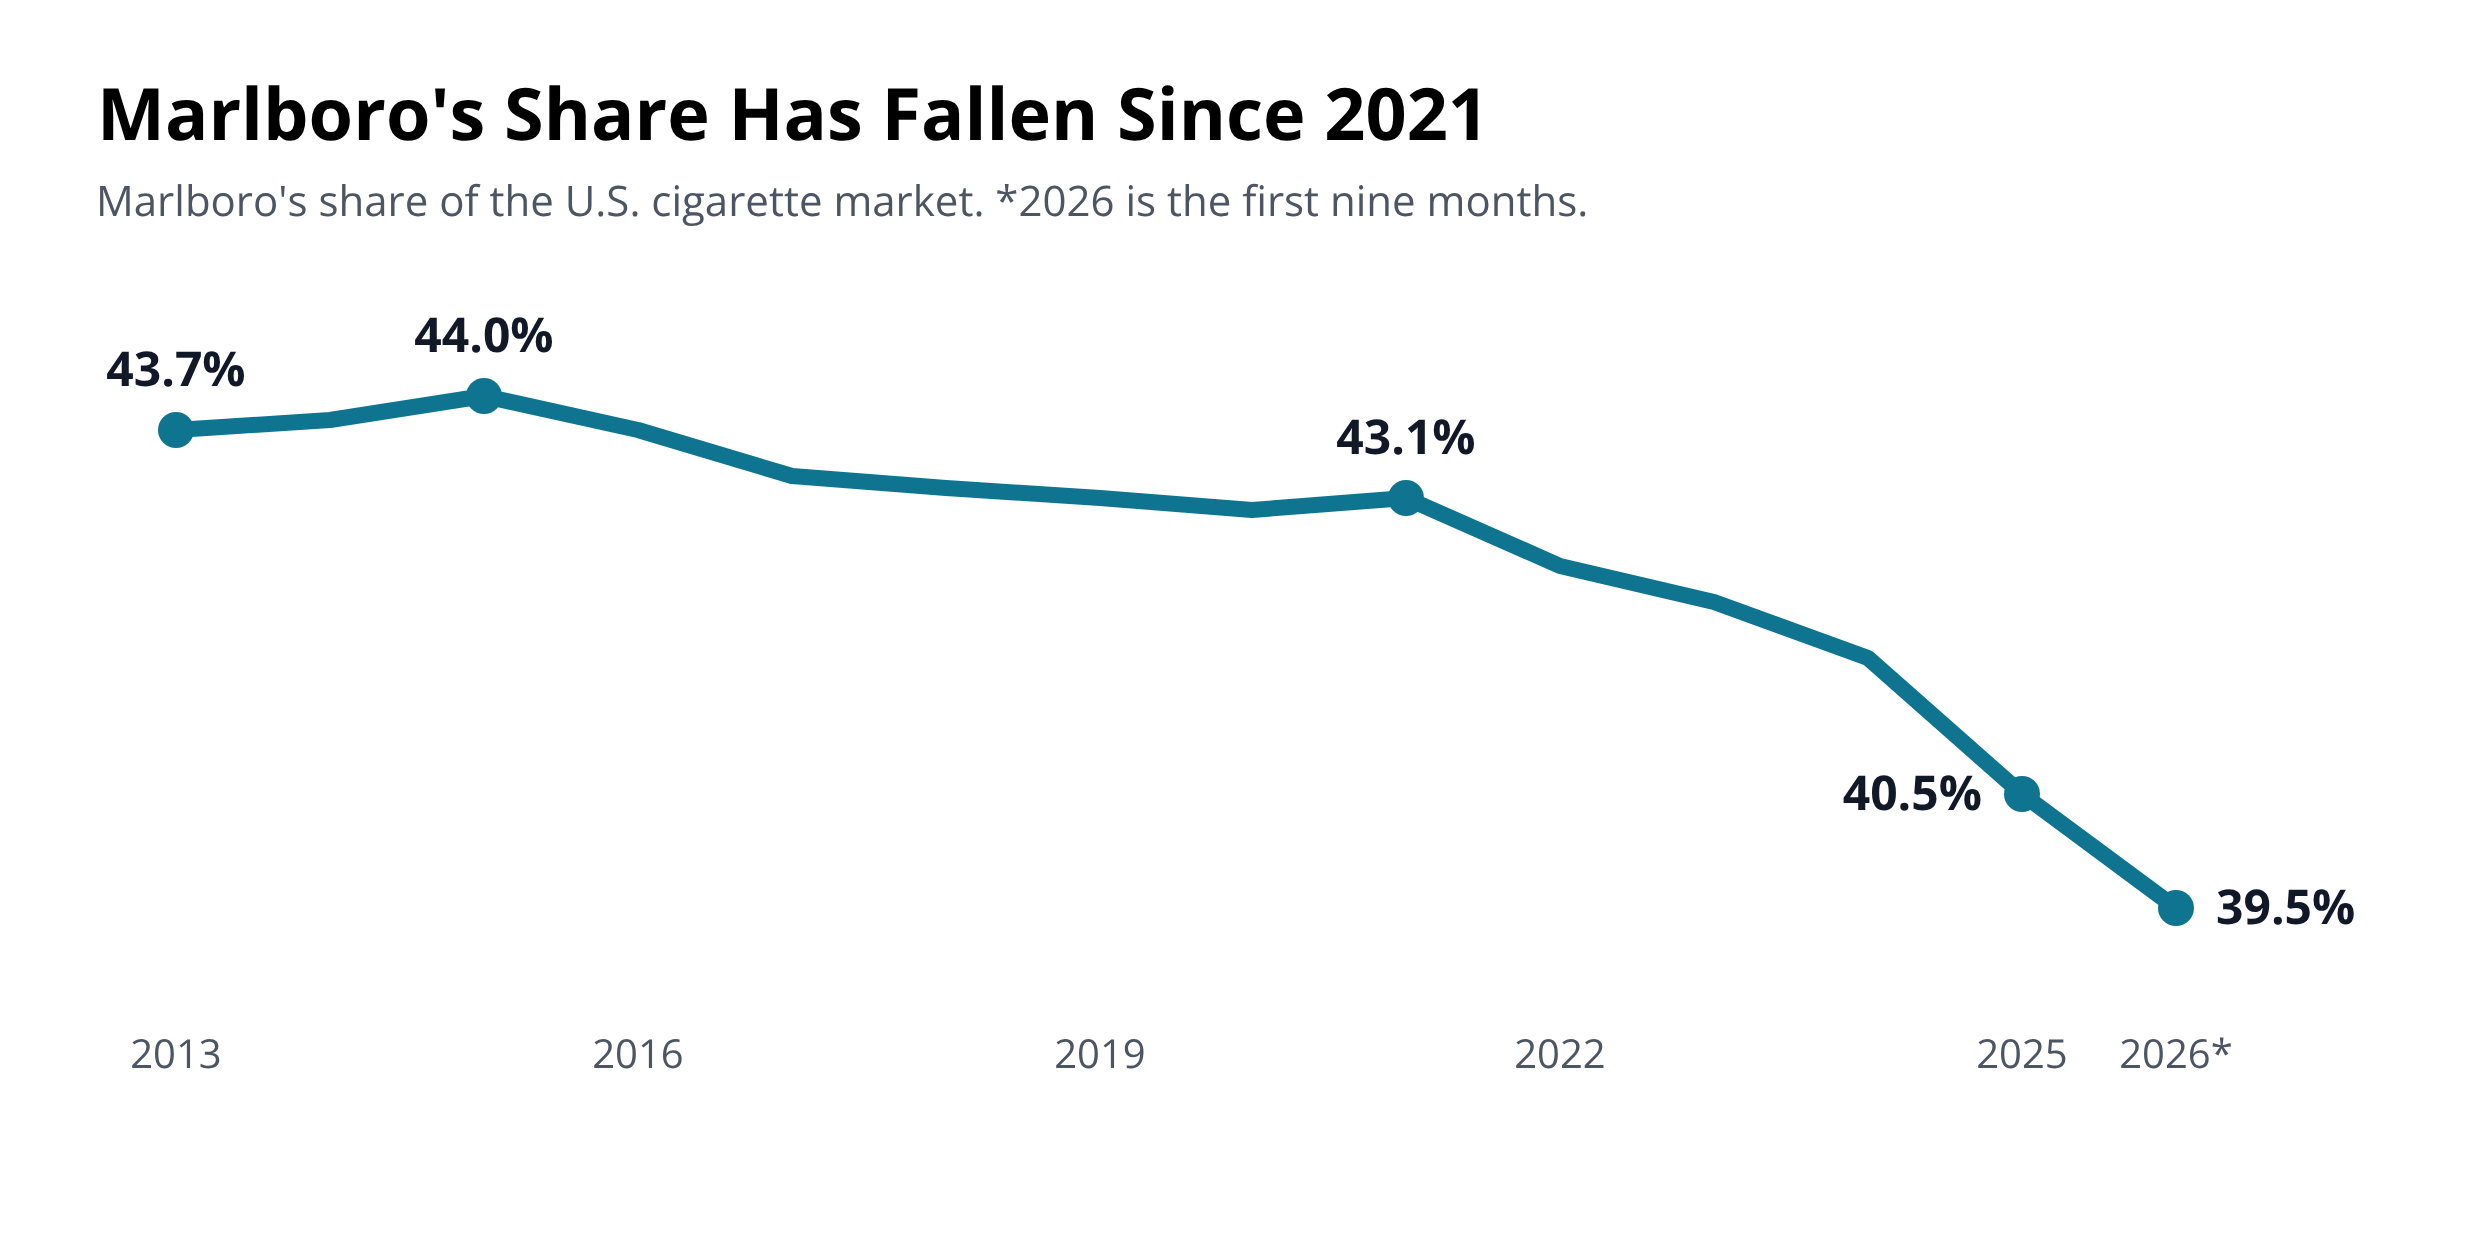
Price increases have limits. After holding near 43% for a decade, Marlboro's share of U.S. cigarettes has slipped to 39.5% this year as smokers trade down to cheaper brands. That suggests each price increase now pushes away more customers, and cigarette margins near 65% leave less room to rise.
Regulation could return. The nicotine cap was shelved, not killed, and a future administration could revive it along with the menthol ban.
Weight-loss drugs. Early research suggests people taking GLP-1 drugs such as Ozempic and Zepbound smoke less and quit more easily. The evidence is preliminary and no GLP-1 is approved to help people quit, but we are watching it as a longer-term risk.
A large acquisition. If cigarette volumes weaken again, Altria could attempt another big purchase to catch up in smoke-free products. New CEO Sal Mancuso, a 35-year Altria veteran and former CFO, may be more disciplined after the Juul and NJOY losses. Given that history, we still count a large deal as a risk.
Is Altria Stock a Buy at Today's Yield?
Altria's stock has nearly doubled since early 2024, and its yield of 5.7% sits well below its five-year average of 7.8%. When a stable dividend payer's yield falls this far below its norm, the share price has usually run ahead of the dividend, an idea we explain in our guide to dividend yield theory.
Existing holders collecting the yield have little reason to sell. But with much of the good news already in the price, we think this is a time to review position sizes rather than add.
Frequently Asked Questions
Is Altria's dividend safe?
We rate it Borderline Safe (60). Altria pays out about 75% of adjusted earnings, carries net debt of about 1.6 times EBITDA and holds a BBB+ credit rating, so the dividend looks secure for the next several years. The longer-term risk is the slow decline of U.S. cigarette smoking with no obvious replacement products in Altria's portfolio today.
We rate it Borderline Safe (60). Altria pays out about 75% of adjusted earnings, carries net debt of about 1.6 times EBITDA and holds a BBB+ credit rating, so the dividend looks secure for the next several years. The longer-term risk is the slow decline of U.S. cigarette smoking with no obvious replacement products in Altria's portfolio today.
How much is Altria's dividend?
Altria pays $1.11 per share each quarter, or $4.44 a year. At the October 30, 2026 price of $78.03, that is a 5.7% yield.
Altria pays $1.11 per share each quarter, or $4.44 a year. At the October 30, 2026 price of $78.03, that is a 5.7% yield.
When does Altria pay its dividend?
Altria pays quarterly, in January, April, July and October. It usually announces its annual raise in August.
Altria pays quarterly, in January, April, July and October. It usually announces its annual raise in August.
Has Altria ever cut its dividend?
Not in the sense that matters to shareholders. Its per-share dividend fell in 2008 when it spun off Philip Morris International, but shareholders received PMI shares that more than replaced the lost income. Altria has raised its dividend 61 times in the past 57 years.
Not in the sense that matters to shareholders. Its per-share dividend fell in 2008 when it spun off Philip Morris International, but shareholders received PMI shares that more than replaced the lost income. Altria has raised its dividend 61 times in the past 57 years.
How fast does Altria grow its dividend?
About 4% a year over the past five years. The company targets mid-single-digit annual dividend growth through 2028.
About 4% a year over the past five years. The company targets mid-single-digit annual dividend growth through 2028.
Looking for other high-yield ideas? See our list of high dividend stocks, ranked by Dividend Safety Score.
We update this page each quarter after Altria reports earnings, and whenever our Dividend Safety Score changes.